

Loan Calculator
Calculate monthly payment, total payment, and total interest for a loan.
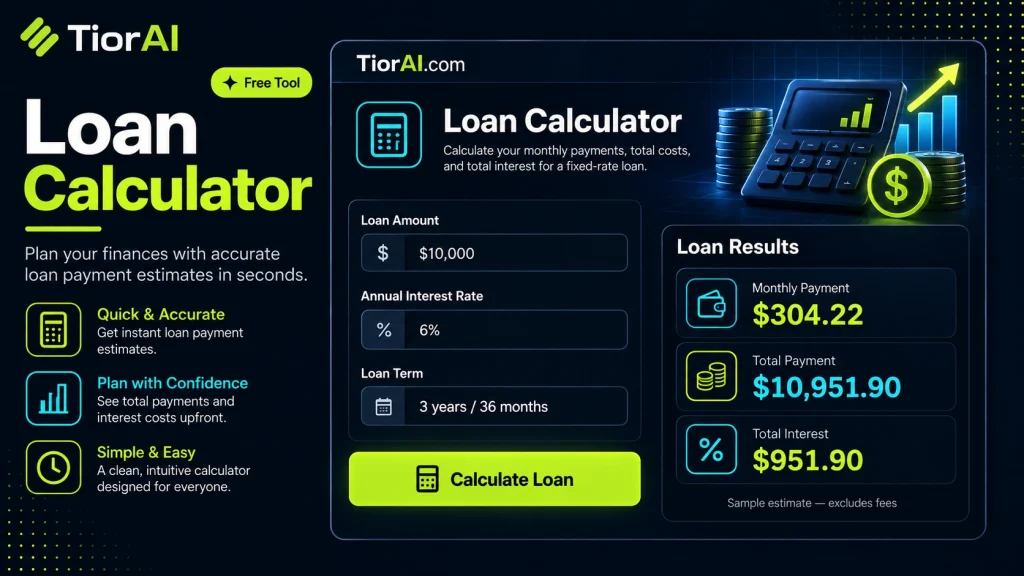
| Measure | Amount |
|---|---|
| Monthly Payment | — |
| Total Payment | — |
| Total Interest | — |
How to use it
- Enter Your Values Input your numbers or parameters into the Loan Calculator. Fill in all required fields for an accurate calculation.
- Calculate Results Click the calculate button to process your inputs. The Loan Calculator delivers instant, accurate results.
- Review and Use Review your calculated results, explore the breakdown, and copy or share the output for your needs.
Tip The Loan Calculator rounds results automatically, but you can use the full decimal output for precision work.
Understanding Loan Calculations
A loan calculator is based on the fundamental formula used to determine the monthly payment amount for a loan. The calculation typically uses the amortization formula, which accounts for the principal amount, interest rate, and loan term.
The core formula for a fixed-rate loan monthly payment is:
M = P × (r(1 + r)^n) / ((1 + r)^n - 1)
- M = monthly payment
- P = principal loan amount
- r = monthly interest rate (annual rate divided by 12)
- n = total number of payments (loan term in months)
This formula calculates the fixed monthly payment that fully amortizes the loan over the specified term, meaning the loan balance reaches zero at the end of the term.
Understanding this calculation is important because it helps borrowers plan their finances by knowing exactly how much they will pay each month. It also allows comparison between different loan offers by adjusting variables like interest rate or loan duration.
In real-world contexts, this calculation is essential for mortgages, auto loans, personal loans, and any other installment-based credit. Lenders use it to set payment schedules, and borrowers use it to assess affordability and total interest costs.
How Loan Calculations Work
Loan calculators use a standard amortization formula to determine your monthly payment based on the loan amount, interest rate, and term. The formula breaks down each payment into principal and interest, ensuring the loan is fully paid off by the end of the term. This calculation is critical for borrowers to understand their financial commitments and for lenders to structure repayment schedules.
When to Use a Loan Calculator
- Planning your monthly mortgage payments before buying a home.
- Estimating car loan payments to fit your budget.
- Comparing loan offers with different interest rates or terms.
- Budgeting for personal or student loan repayments.
Common Mistakes to Avoid
- Entering the annual interest rate directly without converting it to a monthly rate can lead to incorrect results.
- Overlooking additional costs like fees or insurance that affect your total monthly payment.
Using a loan calculator provides a clear picture of your repayment obligations, helping you make informed financial decisions. Always double-check your inputs and consider all associated costs for the most accurate estimate.
Common use cases
- Mortgage Loan Calculation
- Auto Loan Payment
Frequently asked questions
Reviews and questions
Whether this tool gave people the answer they needed, and what they asked about it.
Sign in to review this tool.
Sign In to ReviewNo reviews yet
Be the first to say whether this tool gave you what you needed.
Ask how to read the result, or what the tool does with an edge case — or answer someone else.
Sign In to AskNo questions yet
Not sure how to read a result? Be the first to ask.